Telehealth Giant Posts $890M Quarter But Loses Money as Weight-Loss Drug Strategy Squeezes Margins
Hims & Hers' 49% revenue surge masks profitability challenges as the company pivots from high-margin compounded medications to branded pharmaceutical partnerships with Eli Lilly and Novo Nordisk.
Digital health company Hims & Hers reported third-quarter revenue of $890.4 million, marking a 49% year-over-year increase, but the telehealth platform simultaneously posted a $33 million net loss and missed Wall Street earnings per share expectations. According to stock strategist Ethan Feller of Zacks Investment Research, the company "lost 14 cents a share against an expected gain of six cents, its third big miss in a row." The mixed financial results underscore the growing pains facing direct-to-consumer health platforms as they navigate the transition from compounded medications to branded pharmaceutical distribution.
The San Francisco-based company's subscriber base grew to nearly 2.8 million, up 13% from the previous year, yet its gross margin fell sharply to 57% from 74% a year earlier. Company executives attributed the margin compression primarily to an increasing mix of lower-margin brand-name weight-loss drugs in their product portfolio, signaling a fundamental shift in the company's business model.
Strategic Pivot to Branded Pharmaceuticals
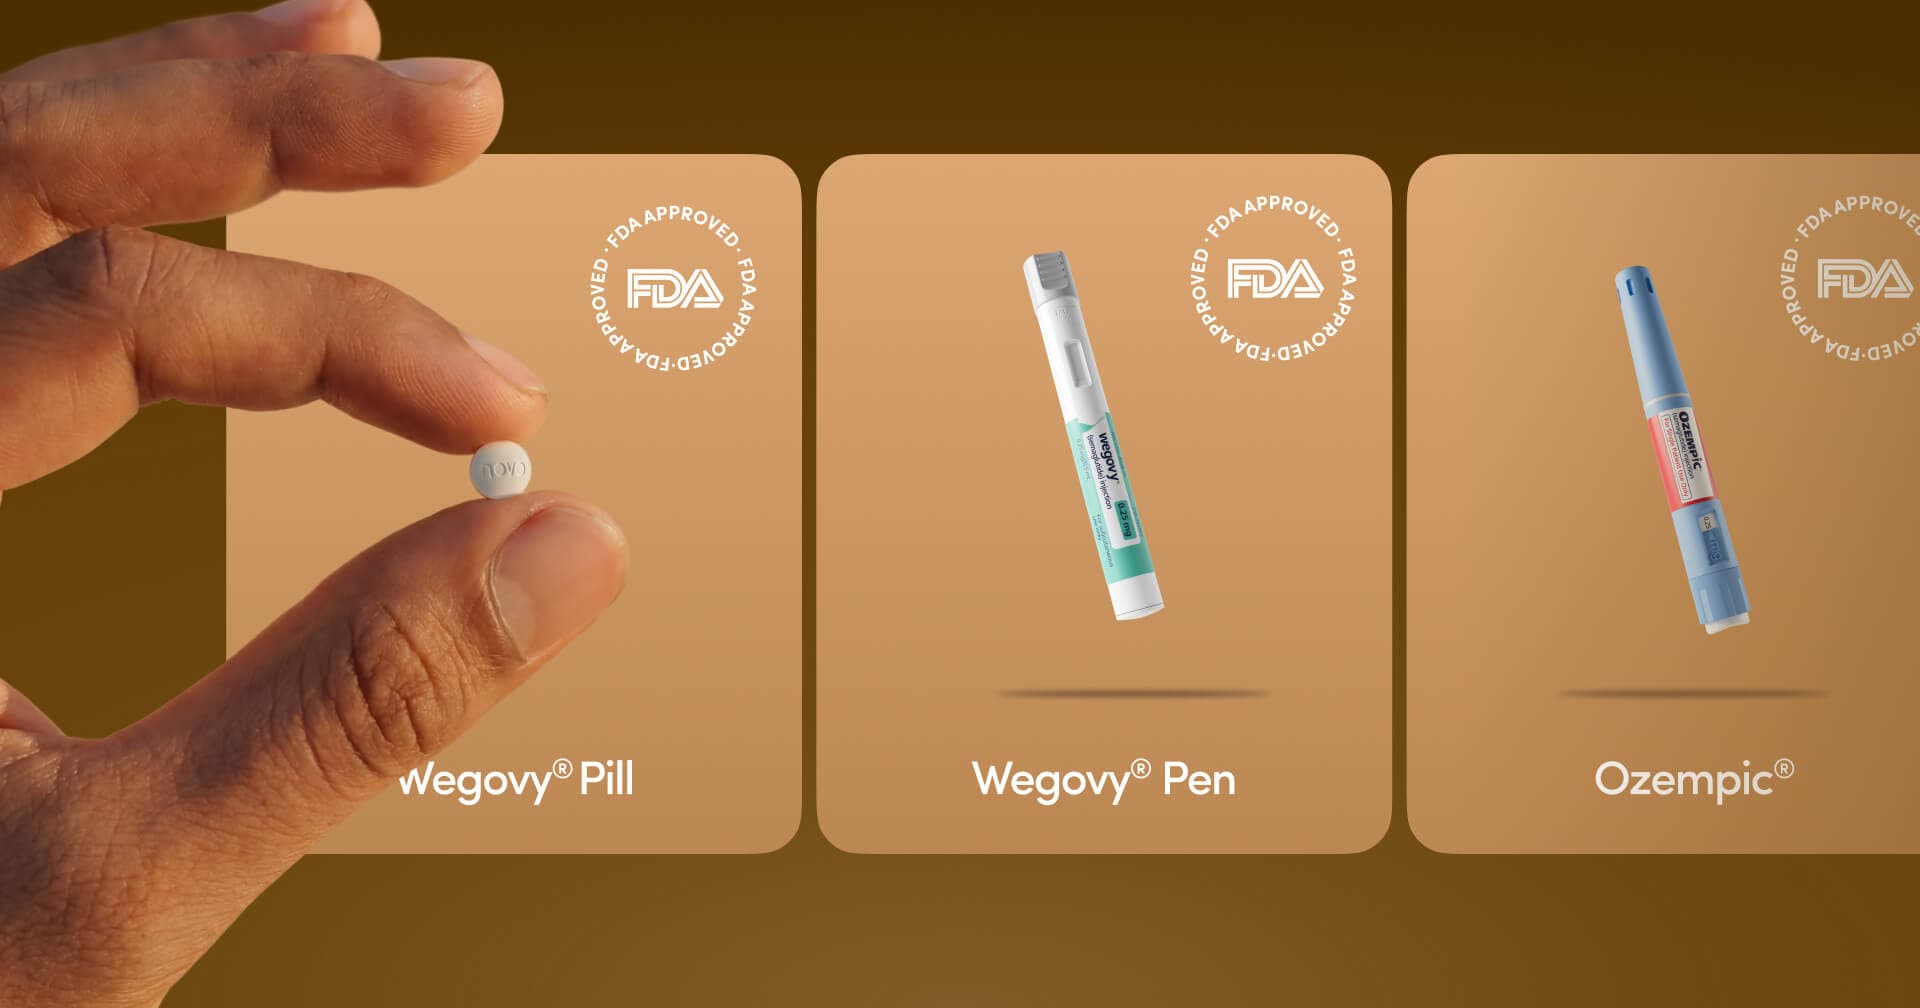
Hims & Hers has forged new partnerships with pharmaceutical giants Eli Lilly and Novo Nordisk to offer branded obesity treatments directly through its platform. Previously, the drugs were only available to patients if they left the site and went to Lilly's direct-to-consumer platform, LillyDirect, but the new arrangement allows Hims & Hers to maintain the customer relationship throughout the treatment journey.
The company also launched testosterone replacement therapy during the third quarter and plans to introduce a "Peptides Plus" offering later in November, featuring sermorelin and NAD+ peptides. These expansions into metabolic health treatments represent the platform's attempt to diversify beyond its original focus areas while capturing growing consumer demand for weight management solutions.
The strategic expansion comes with financial trade-offs. Hims & Hers excluded $18 million from Q3 revenue due to scaling of membership revenue in its weight loss offering, with that amount expected to be recognized in the fourth quarter. The company has also taken aggressive strategic pricing and marketing actions specifically in the U.K. and Germany markets.
AI Infrastructure as Margin Defense
CEO Andrew Dudum emphasized the company's investment in what he termed an "AI-native experience" designed to improve infrastructure efficiency and enhance the customer platform. This technological focus appears central to the company's strategy for offsetting margin pressure as it scales operations across four continents.
Despite the profitability challenges, Hims & Hers reported adjusted EBITDA of $82.4 million for the quarter, compared to $78.4 million in the prior year period. The company has tightened its full-year guidance, now projecting revenue between $3.13 billion and $3.15 billion, while reducing its adjusted EBITDA outlook to a range of $257 million to $277 million.
Market Implications
The financial performance illustrates a critical inflection point for telehealth platforms: rapid subscriber growth and revenue expansion don't automatically translate to profitability when business models shift toward lower-margin pharmaceutical distribution. The company's ability to leverage AI-driven automation and scale efficiencies will likely determine whether it can sustain growth while returning to consistent profitability.
For the broader digital health sector, Hims & Hers' experience offers insight into the challenges of competing in pharmaceutical distribution while maintaining the margins that made telehealth platforms attractive to investors. The company's planned introduction of flexible multi-month subscriptions suggests ongoing experimentation with pricing and service models to balance growth with financial sustainability.
Sources
Companies in this article

Google Search
Follow Health AI Central on Google
Choose Health AI Central as a preferred source, and Google is more likely to show our reporting in Top Stories.
Reporting & accountability
How we maintain accuracy
Health AI Central separates reported facts, analysis, and public-source data. Readers can review our standards, request a correction, or consult the relevant research methodology before relying on a claim.